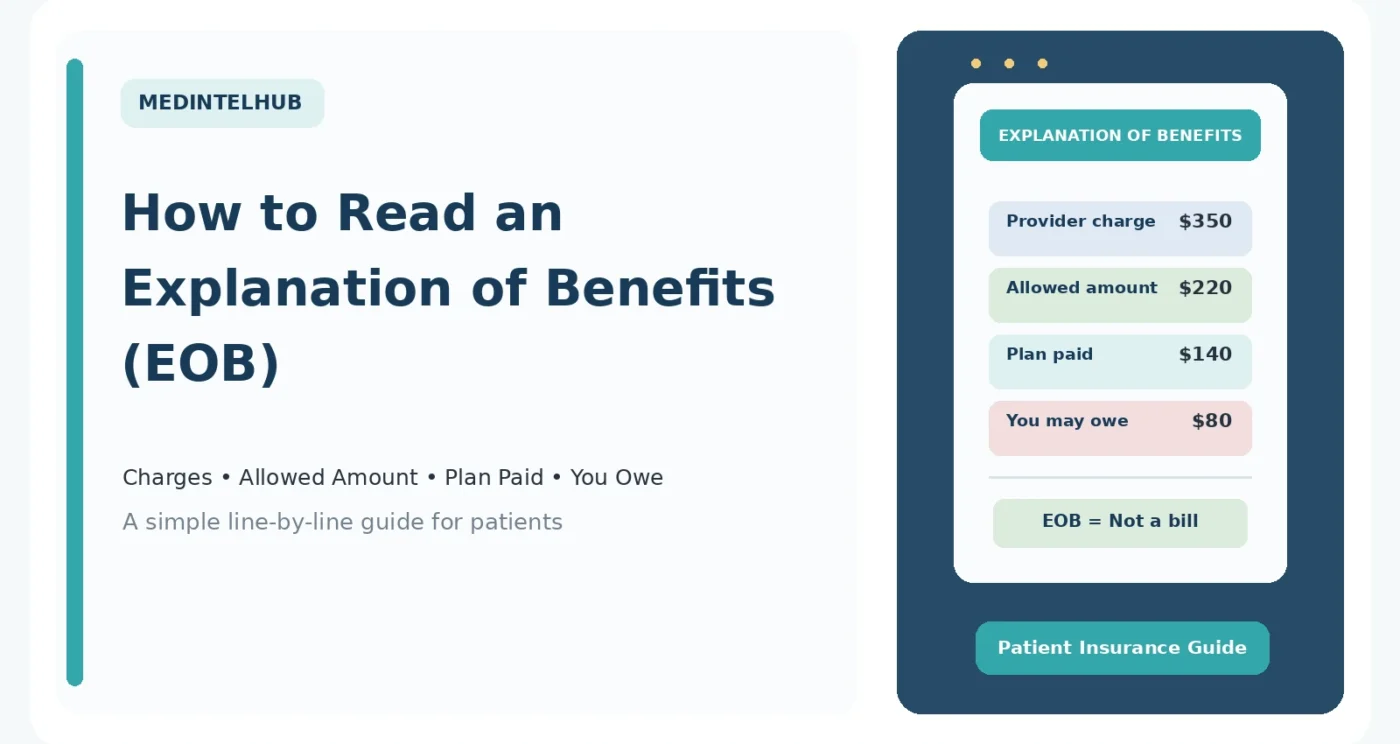
An Explanation of Benefits can look like a medical bill.
It may show a doctor’s name, several dollar amounts, insurance adjustments, and a number labeled “you owe” or “patient responsibility.”
But an Explanation of Benefits, or EOB, is not a bill.
It is a statement from your health plan explaining how it processed a healthcare claim.
The Centers for Medicare & Medicaid Services explains that an EOB shows information such as the provider’s charges, the amount the plan allows, what the insurer paid, and what the patient may owe.
The easiest way to read an EOB is not to stare at every number at once.
Work through it in order.
Important: Health plans use different EOB layouts and terminology. The exact column names may vary. If a claim, denial, adjustment, or patient-responsibility amount does not make sense, contact the health plan and provider before assuming the amount is correct.
Step 1: Make Sure You Are Looking at an EOB, Not a Bill
Start with the document itself.
An EOB usually comes from your insurance company or health plan.
A medical bill usually comes from a doctor, hospital, laboratory, imaging center, or other healthcare provider.
The EOB explains how the insurer handled the claim.
The medical bill asks you to pay a balance.
CMS specifically states that an EOB is not a bill.
You generally want to compare the EOB with the provider’s bill before paying a balance.
Step 2: Check the Patient and Health Plan Information
Before looking at the charges, make sure the basic information is correct.
An EOB may include:
- Patient name
- Health plan name
- Member or subscriber information
- Provider name
- Date of service
- Claim number
CMS notes that the claim number is a reference number connected with the claim.
If you call the insurance company with a question, having that number available can make the conversation easier.
Step 3: Confirm That You Recognize the Provider
Look at the provider or facility listed on the EOB.
Make sure you recognize the name.
Sometimes the name will be different from the one you remember seeing on the building or patient portal.
For example, a hospital visit can generate separate claims from:
- The hospital
- A physician
- A radiologist
- A pathologist
- An anesthesiologist
- A laboratory
That does not automatically mean the claim is wrong.
But if you do not recognize the provider or service at all, investigate it.
Step 4: Check the Date of Service
The date of service tells you when the healthcare service occurred.
Compare it with your own records.
If the EOB shows a date when you did not receive care, call the provider or health plan.
Also remember that one healthcare episode can produce services on several dates.
For example, an office visit may happen on one day while a laboratory processes a specimen on another.
Step 5: Read the Service Description
The EOB may provide a short description of the service.
Examples might include:
- Office visit
- Laboratory test
- Imaging
- Preventive screening
- Therapy
- Procedure
The description may be general rather than detailed.
If you are unsure what a service refers to, contact the provider or health plan and ask.
Step 6: Find the Provider Charge
The provider charge, sometimes called the billed amount, is what the healthcare provider submitted on the claim.
For example:
Provider charge: $350
This is not necessarily what the insurer will pay.
It is also not necessarily what you owe.
This is one of the biggest sources of confusion when reading an EOB.
Step 7: Find the Allowed Amount
The next number may be labeled:
- Allowed amount
- Allowed charge
- Eligible expense
- Payment allowance
- Negotiated rate
HealthCare.gov defines the allowed amount as the maximum amount a health plan will pay for a covered healthcare service under the plan’s rules.
For example:
- Provider charge: $350
- Allowed amount: $220
The insurer’s payment and your cost-sharing are usually calculated using the allowed amount rather than the provider’s original billed charge.
Step 8: Look for the Network Discount or Adjustment
If the provider is in network, the EOB may show an adjustment between the billed amount and the allowed amount.
Using the example above:
- Provider billed: $350
- Allowed amount: $220
- Network or contractual adjustment: $130
That $130 is not automatically money the patient owes.
For covered in-network services, contracted providers generally cannot simply bill the patient for a contractual adjustment.
Out-of-network claims can be different and may involve other plan rules or balance-billing issues.
Step 9: Check the Deductible
A deductible is an amount you generally pay for certain covered services before the health plan begins paying its share.
HealthCare.gov explains that after meeting an applicable deductible, a person typically pays a copayment or coinsurance while the insurer pays its share.
Suppose your EOB shows:
- Allowed amount: $220
- Applied to deductible: $120
That means $120 of the allowed amount was assigned to your deductible under the plan’s rules.
Not every service is necessarily subject to a deductible in the same way.
Some preventive services may be covered before the deductible is met.
You can review the definition on the HealthCare.gov deductible page.
Step 10: Look for a Copayment
A copayment, often called a copay, is usually a fixed amount you pay for a covered healthcare service.
Examples might include:
- $25 for a primary care visit
- $50 for a specialist visit
- A fixed amount for urgent care
Your actual plan amounts may be different.
A copayment may also have been collected at the time of the visit.
That is important because an EOB can still show a copay as your responsibility even if you already paid it to the provider.
See the HealthCare.gov copayment definition for more information.
Step 11: Look for Coinsurance
Coinsurance is generally a percentage of the allowed cost that you pay for a covered service.
For example:
- Allowed amount after deductible: $100
- Your coinsurance: 20%
- Your coinsurance amount: $20
HealthCare.gov defines coinsurance as a percentage of covered healthcare costs that a person pays after meeting the applicable deductible.
You can review additional examples on the HealthCare.gov coinsurance page.
Step 12: Find What the Insurance Company Paid
The insurer’s payment may be labeled:
- Paid by insurer
- Plan paid
- Insurance payment
- Benefit paid
CMS describes this as the amount the health plan pays toward the claim.
A $0 insurance payment does not always mean the claim was denied.
For example, the allowed amount could have been entirely assigned to the patient’s deductible.
That is why you need to read the full EOB rather than looking only at the insurer-payment column.
Step 13: Find the Patient Responsibility
The most important number for many patients is usually labeled:
- You owe
- Patient responsibility
- Patient balance
- Your share
This amount may include:
- Deductible
- Copayment
- Coinsurance
- Certain non-covered amounts
- Some out-of-network costs
But remember:
The EOB does not necessarily know whether you already paid part of this amount directly to the provider.
CMS specifically notes that a patient may already have paid some of the patient balance.
That is one reason you should compare the EOB with the provider’s actual bill.
A Simple EOB Example
Suppose you received an in-network specialist service.
Your EOB might look something like this:
- Provider charge: $400
- Allowed amount: $250
- Network adjustment: $150
- Applied to deductible: $100
- Remaining allowed amount: $150
- Your coinsurance: 20% of $150 = $30
- Insurance payment: $120
- Total patient responsibility: $130
In this example, the patient does not automatically owe the original $400 charge.
The cost-sharing calculation is based on the plan’s allowed amount.
This is only an illustration. Actual claims can be calculated differently depending on the plan, service, network, deductible, copayment, coinsurance, benefit limits, and other coverage rules.
Step 14: Read Any Remark or Explanation Codes
If a claim was reduced, denied, or processed differently than expected, look for a remark code or explanatory note.
CMS explains that an EOB may include a short remark code that provides more information about the claim.
The explanation for the code may appear:
- At the bottom of the EOB
- On another page
- In a separate explanation section
Do not ignore the remark code.
It may explain why the insurer did not pay what you expected.
What if the EOB Says the Claim Was Denied?
First, identify the reason.
A denied claim can involve issues such as:
- Coverage
- Prior authorization
- Network status
- Missing information
- Medical-necessity requirements
- Duplicate billing
- Coordination of benefits
A denial does not always mean the patient automatically owes the full amount.
The provider may need to correct the claim, submit more information, or challenge the payer’s decision.
For a deeper look at this process, see our MedIntelHub guide Claim Denials: A Practical Prevention and Follow-Up Checklist.
An EOB may indicate that the payer reduced or denied payment because prior authorization was missing or because the service did not match the authorization.
Do not assume that automatically makes the entire charge the patient’s responsibility.
The provider and payer may need to review what happened.
For more information, see our MedIntelHub article Prior Authorization: A Clear Guide for Patients and Practices.
Step 15: Compare the EOB With the Medical Bill
This is one of the most useful things you can do.
When the provider’s bill arrives, compare:
- Patient name
- Provider
- Date of service
- Services
- Insurance payment
- Adjustments
- Patient responsibility
- Payments you already made
CMS recommends checking the bill against the EOB to make sure the services and amounts match.
CMS also states that the provider bill should not be higher than the EOB patient balance for the claim without an explanation.
If the EOB says you owe $80 and the provider sends a $300 bill, ask questions before paying the difference.
You can review the official CMS guide to reading a medical bill.
Why Might the Bill and EOB Be Different?
There are several possible explanations.
For example:
- The provider sent the bill before insurance finished processing the claim
- The provider’s statement has not yet reflected an insurance adjustment
- You already paid a copay
- A claim was reprocessed
- Secondary insurance has not processed the claim yet
- The provider or payer made an error
Do not assume every mismatch means fraud or intentional overbilling.
But do ask for an explanation.
Step 16: Check Your Deductible Progress
Some EOBs show how much of your annual deductible you have met.
This can help you understand why the same type of service may cost you more early in the year and less later.
For example, once an applicable deductible has been met, the plan may begin paying a greater portion of covered services while you pay copayments or coinsurance.
Check your plan documents because not every benefit follows the same deductible rules.
Step 17: Check Your Out-of-Pocket Progress
Some EOBs also show progress toward your annual out-of-pocket maximum.
HealthCare.gov explains that the out-of-pocket maximum is generally the most a person has to pay for covered in-network services during a plan year before the plan pays 100% of covered benefits for the remainder of that year.
Not every expense counts toward the maximum.
For example, premiums and certain non-covered or out-of-network costs generally do not count.
What About Out-of-Network Claims?
Out-of-network EOBs can be more complicated.
The provider’s charge may be higher than the plan’s allowed amount.
Depending on the situation, the patient may have greater cost-sharing or may potentially face balance billing.
However, federal protections under the No Surprises Act prohibit many forms of unexpected out-of-network billing involving emergency services and certain services received at in-network facilities.
CMS provides current information on the No Surprises Act patient-protection page.
If an out-of-network bill is unexpectedly high, review the EOB before assuming the balance is valid.
What if You Have Original Medicare?
If you have Original Medicare, you generally receive a Medicare Summary Notice, or MSN, for Part A and Part B claims rather than a standard commercial-insurance EOB.
Medicare states that the MSN is not a bill.
It shows:
- Services or supplies billed to Medicare
- What Medicare paid
- The maximum amount you may owe the provider
You can learn more on the Medicare Summary Notice page.
Medicare Advantage and Medicare drug plans use EOB-style notices for claims and costs.
What if You Do Not Recognize a Claim?
If the EOB lists care you do not remember receiving, investigate it.
Start by checking whether the unfamiliar provider was connected with another service you did receive.
If you still do not recognize it:
- Contact the provider listed on the claim.
- Contact the health plan.
- Ask what service was billed.
- Keep notes of the conversation.
Do not ignore unfamiliar claims simply because the EOB says you owe $0.
Questions to Ask Your Insurance Company
If an EOB does not make sense, useful questions include:
- What does this adjustment mean?
- Why was this amount applied to my deductible?
- Why did the plan pay $0?
- Why was the service denied?
- Why is the provider listed as out of network?
- What does this remark code mean?
- Was prior authorization required?
- Should the provider correct and resubmit the claim?
- Do I have appeal rights?
- How much have I met toward my deductible?
- How much have I met toward my out-of-pocket maximum?
Write down the name of the representative, date of the call, and any reference number they provide.
Questions to Ask the Provider’s Billing Office
You might ask:
- Has insurance finished processing this claim?
- Does your bill reflect the insurance adjustment?
- Did you receive the insurer’s payment?
- Did you receive a denial?
- Are you correcting or appealing the claim?
- Did you apply the payment I already made?
- Why is the bill different from my EOB?
The provider’s billing office and the insurance company see different parts of the process, so sometimes you need information from both.
Do Not Pay an EOB
An EOB is informational.
You do not send payment to the EOB itself.
CMS recommends waiting for the provider’s bill and then comparing that bill with the EOB.
If you already paid a copay or another amount at the time of service, make sure the provider’s bill gives you credit for that payment.
A Quick EOB Reading Checklist
When an EOB arrives, use this order:
- Confirm that it is an EOB, not a bill.
- Check the patient name.
- Check the provider.
- Check the date of service.
- Make sure you recognize the service.
- Find the provider charge.
- Find the allowed amount.
- Review the network or contractual adjustment.
- Check deductible, copay, and coinsurance.
- See what insurance paid.
- Find your patient responsibility.
- Read all remark or denial codes.
- Check deductible and out-of-pocket progress.
- Compare the EOB with the provider’s bill.
- Ask questions before paying anything that does not match.
The Bottom Line
An Explanation of Benefits becomes much easier to read when you stop treating it like one giant page of numbers.
Start with the patient, provider, date, and service.
Then move through the money in order:
Provider charge → allowed amount → adjustment → deductible → copay or coinsurance → insurance payment → patient responsibility.
After that, read any remark or denial codes.
Finally, compare the EOB with the provider’s actual bill.
An EOB is not a bill, and the provider’s original charge is not automatically what you owe.
If the numbers do not match, a service looks unfamiliar, or a claim was denied, contact the provider and health plan before assuming the balance is correct.
The goal is not to become an insurance expert.
It is to understand enough of the claim to know what insurance paid, what you may owe, and when something deserves a second look.
Sources and References
- Centers for Medicare & Medicaid Services — How to Read an Explanation of Benefits. Official guide covering provider charges, allowed charges, insurer payments, patient balance, claim information, and remark codes.
- Centers for Medicare & Medicaid Services — How to Read Your Medical Bill. Guidance on comparing a medical bill with an EOB and checking patient responsibility before paying.
- HealthCare.gov — Allowed Amount. Definition of the maximum amount a plan recognizes for a covered healthcare service.
- HealthCare.gov — Deductible. Explanation of how deductibles generally work.
- HealthCare.gov — Copayment. Definition of fixed cost-sharing amounts for covered services.
- HealthCare.gov — Coinsurance. Definition of percentage-based cost sharing.
- HealthCare.gov — Out-of-Pocket Maximum. Information about annual limits on covered in-network cost sharing.
- Centers for Medicare & Medicaid Services — Know Your Rights When Using Health Insurance. Information about federal protections against many types of surprise out-of-network bills.
- Medicare.gov — Medicare Summary Notice. Official explanation of the notice Original Medicare beneficiaries receive for Part A and Part B claims.
Editorial Disclaimer
MedIntelHub provides healthcare, insurance, medical billing, and patient-education information for educational purposes only.
Insurance benefits, allowed amounts, network rules, deductibles, copayments, coinsurance, claim-processing rules, appeal rights, and patient responsibility vary by health plan and individual circumstances.
An EOB is not a guarantee that every claim amount is correct or that a payer decision cannot be reconsidered. If you have questions about a claim, denial, or medical bill, contact the applicable health plan and healthcare provider.
This article does not provide medical, legal, financial, or insurance-contract advice.
For more information about our publication, visit About MedIntelHub.
David Bennett
David Bennett is an author at MedIntelHub, where he creates clear, practical, and well-researched content about healthcare, medical billing, insurance, and patient education. His goal is to make complex healthcare topics easier for readers to understand and use in everyday situations. David emphasizes accuracy, transparency, and reliable sourcing, using information from trusted organizations and official healthcare resources whenever possible. Content published by David is intended for educational purposes and should not replace advice from qualified medical, legal, or healthcare professionals.